Ask your projects data anything. Get answers in seconds. Plexa MCP Connector is live. See it in action
Construction Retention: What Builders and Subbies Need to Know
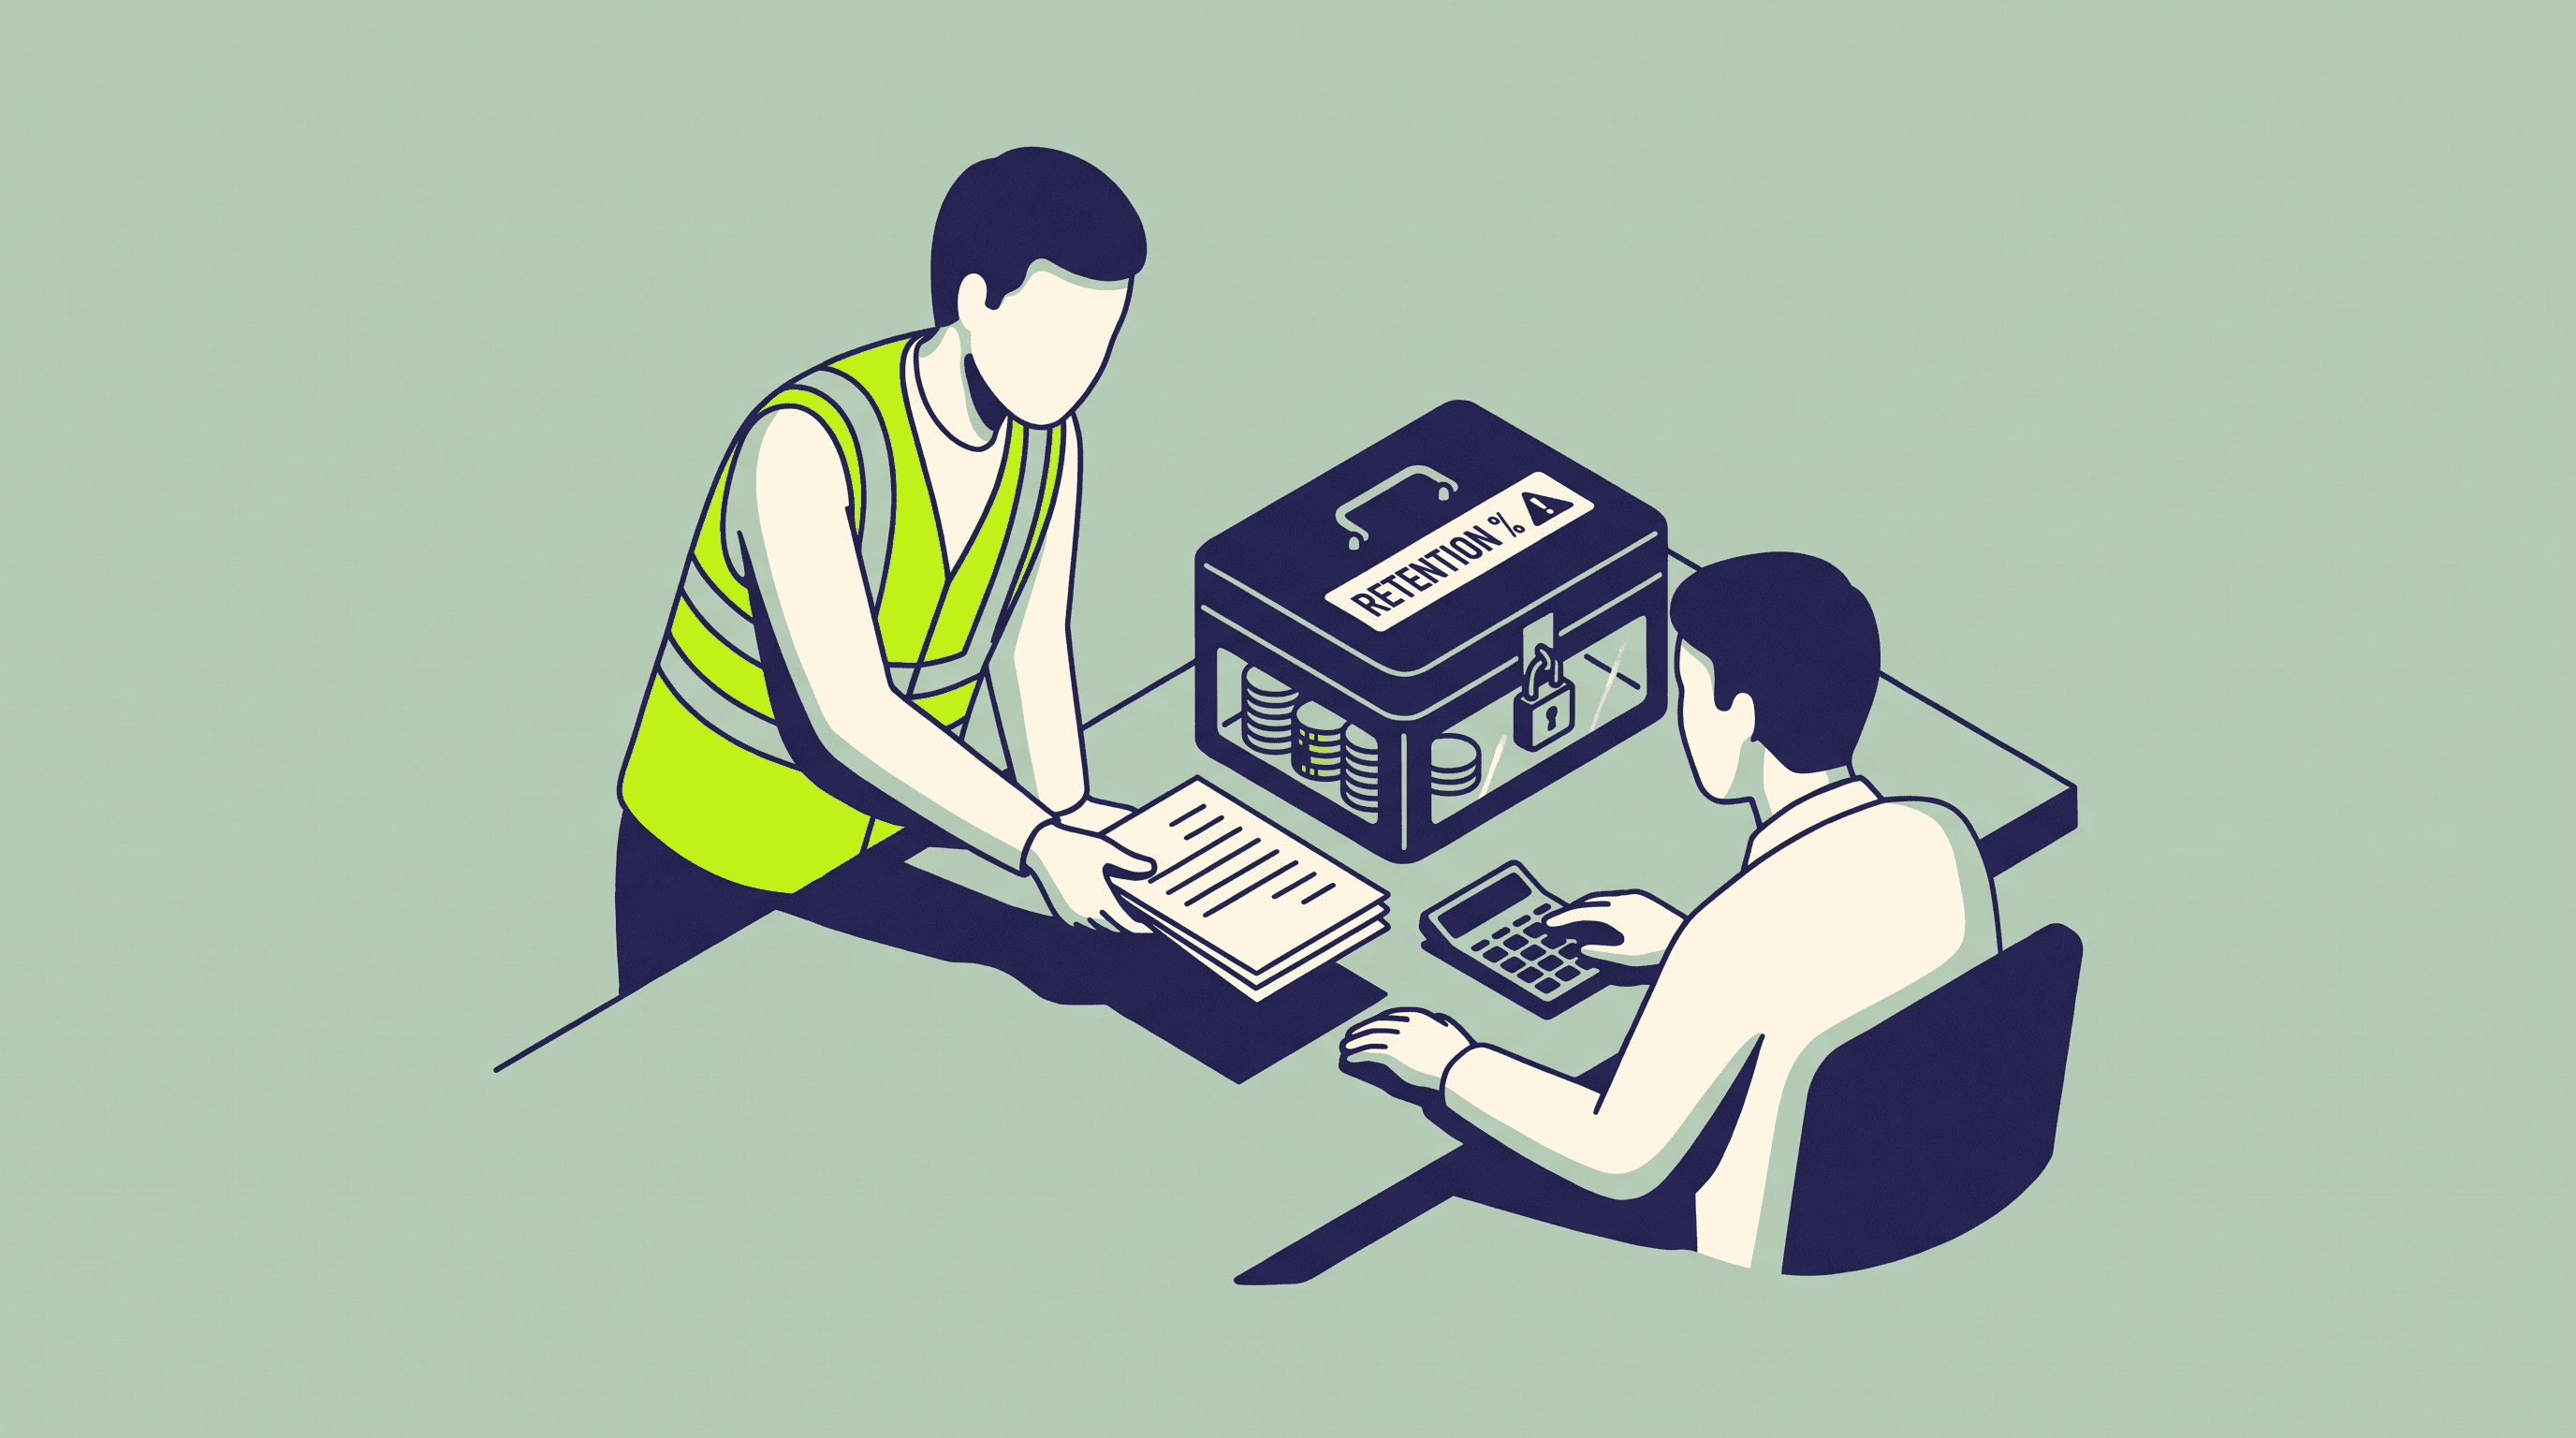
Retention is the silent cash-flow killer for subcontractors and a risk management lever for head contractors. Here is how it works, when it releases, and why most teams still track it in a spreadsheet.
The electrical subcontractor on a $40M commercial fit-out in Brisbane finishes his final fix, gets his practical completion signed off, and submits his last progress claim. Three weeks later the payment lands, minus the 5% retention the head contractor has held since month one. That is $87,000 of his money sitting in a trust account for another twelve months while the defects liability period runs. He has already paid his sparkies, bought the materials, covered the insurance. The retention is pure cash out of his business for a year, earning him nothing.
He is not unusual. Every subcontractor on every major project in Australia carries this cost. Construction retention is the mechanism that protects head contractors against defective work, but for the businesses on the other side of the ledger, it is a silent drag on cash flow that compounds across every active project.
What retention actually is
Retention is a percentage of each progress payment withheld by the head contractor (or principal) as security against defects. The standard rate across most Australian construction contracts is 5% of each progress claim, deducted from every payment certificate until the total retention reaches a capped amount, typically 5% of the subcontract value.
The withheld money serves a specific purpose. If the subcontractor’s work is defective and they fail to return to rectify it, the head contractor can use the retention funds to engage someone else to fix the problem. It is a financial lever, not a penalty. The money belongs to the subcontractor. It is held, not forfeited.
5%
The standard retention rate across most Australian construction contracts, deducted from every progress claim until the cap is reached.
When retention releases
Release follows a two-stage pattern on most projects. The first portion, typically half the total retention held, releases at practical completion. The second half releases at the end of the defects liability period (DLP), which usually runs 12 months after practical completion, though some contracts specify longer periods for specific elements like structural waterproofing.
In Queensland, the Building Industry Fairness (Security of Payment) Act 2017 requires that 50% of retention releases at practical completion, with the balance due at the end of the DLP unless there is a legitimate dispute.[1] The head contractor must notify the subcontractor when the DLP ends using the prescribed form, and failure to do so is an offence.
In NSW, the release mechanism is governed by the contract terms, but the Building and Construction Industry Security of Payment Act 1999 gives subcontractors the right to make a payment claim for unreleased retention.[2] If the head contractor does not release the funds after the DLP expires, the subcontractor can trigger adjudication within 10 to 28 days, a far faster path than court proceedings.
The problem is not the law. It is the gap between what the contract says and what actually happens on site.
“Trust accounts are aimed at ensuring money paid by those at the top of the chain is secured for the benefit of subcontractors, ensuring they are paid on time and in full.”
Queensland Building and Construction Commission, Trust Accounts Framework[3]
Trust accounts: NSW and QLD requirements
Both NSW and Queensland now require retention money to be held in dedicated trust accounts, though the thresholds and structures differ.
In NSW, head contractors on projects valued over $20 million must deposit retention money into a trust account with an authorised deposit-taking institution. The account must be named to include “trust account,” and the head contractor must notify the relevant secretary within 14 days of opening. Quarterly ledger statements must go to every subcontractor whose money is held. Non-compliance carries fines of up to $22,000.[2]
Queensland introduced its trust account framework on 1 March 2021 under the Building Industry Fairness Act.[3] The framework requires two types of accounts: a Project Trust Account (PTA) for each eligible contract to receive and disburse progress payments, and a Retention Trust Account (RTA) to hold cash retention amounts. A single RTA can serve multiple projects, but each PTA is contract-specific. Independent reviews are required at set intervals, and the QBCC actively monitors compliance.
$22,000
Maximum fine in NSW for a head contractor who fails to comply with retention trust account obligations.
NSW Building and Construction Industry Security of Payment Act 1999[2]
These trust frameworks exist for a reason. When a head contractor becomes insolvent, retention money held in a general operating account disappears into the creditor pool. A trust account ringfences it. Given the scale of insolvency in the sector, that distinction matters.
Why insolvency makes retention a live issue
Construction insolvency in Australia is not a hypothetical risk. In the 2024 financial year, 2,832 construction companies entered insolvency, a 28% increase on the previous year and more than double the figure from 2022.[4] Construction consistently accounts for the highest share of corporate insolvencies of any industry in the country.
2,832
Construction companies that entered insolvency in Australia in FY2024, a 28% increase year on year.
Olvera Advisors, 2024 Year-In-Review[4]
For subcontractors, a head contractor collapse without trust-protected retention means lost money, full stop. The work is done, the defects liability clock is running, and the retention sits in a general account that a liquidator will distribute pro rata to all creditors. This is one of the reasons the NSW and QLD trust requirements were introduced, and why subcontractor management now includes financial due diligence on the party holding your money.
How subbies price retention into their bids
No subcontractor absorbs retention as a neutral cost. The 5% withheld on every claim is money that could be earning returns, paying suppliers, or funding the next project. Smart subbies account for it.
The typical adjustments look like this: a loading on the quoted rate to cover the cost of capital tied up in retention, a cash flow buffer built into the programme to cover the 12 to 18 months between practical completion and final release, and in some cases, a negotiated reduction in the retention percentage from 5% to 2.5% in exchange for a bank guarantee or insurance bond.
The result is that retention does not save the head contractor money. It shifts risk, which the subcontractor prices back in. On a project with 30 subcontractors each adding even a modest loading, the cumulative effect on the head contract price is material. Understanding that dynamic is part of managing construction profit margins effectively.
The tracking problem
Here is where retention moves from a legal issue to an operational one. On a project with 30 active subcontracts, the head contractor’s contracts administrator is tracking 30 separate retention balances, each with its own practical completion date, its own DLP expiry, and its own release trigger. Across a portfolio of five or ten concurrent projects, that number climbs into the hundreds.
Most teams track retention in spreadsheets. The spreadsheet does not send alerts when a DLP expires. It does not flag when a release is overdue. It does not connect to the accounts payable workflow that processes the actual payment. The result is predictable: retention releases get missed, subcontractors chase payments they are contractually owed, and disputes arise over amounts that should have been returned months ago.
The Contracts Specialist legal practice in Sydney notes that wrongful withholding of retention after DLP expiry is one of the most common payment disputes in NSW construction.[5] The money is due. The contract says so. But nobody flagged the date, so nobody processed the release.
For the subcontractor, the cost is real. That $87,000 held on one project, multiplied across three or four active contracts, is $250,000 to $350,000 in tied-up capital. For a business running on tight margins, the difference between a retention released on time and one released three months late can be the difference between meeting payroll and drawing on an overdraft.
Where Plexa fits
Plexa’s Finance and Cost Control module tracks retention as part of every subcontract financial commitment. When a progress claim is assessed and approved, the retention deduction calculates automatically against the contract terms. The platform holds a running ledger of retention held, retention released, and retention due for release, linked to each subcontract and each project.
The practical completion milestone and DLP expiry date sit inside the same system. When a release date approaches, the workflow surfaces it. The contracts administrator does not need to remember to check a spreadsheet on the right Friday. The release triggers, the payment queues, and the accounts payable process handles disbursement.
For head contractors managing trust account obligations, the ledger provides the quarterly statements NSW requires and the audit trail Queensland mandates, without manual compilation.
Go back to that electrical subcontractor in Brisbane. In a system where retention tracking is connected to the subcontract, the progress claim, and the DLP milestone, his $87,000 does not sit in a trust account for three months past its release date because someone forgot to check the calendar. It releases when the contract says it should. He gets paid. The head contractor stays compliant. The relationship survives the next tender round.
Related reading
The retention release process connects directly to how builders manage accounts payable and invoice approvals. For the broader picture of managing subcontractor relationships and financial commitments, see our guide to subcontractor management. And for context on why every dollar of tied-up capital matters, read why construction profit margins keep getting tighter.
If you want to see how Plexa tracks retention across your subcontract portfolio, book a 30-minute demo with the Plexa team.
Sources
1. Queensland Building and Construction Commission. Retentions and securities. qbcc.qld.gov.au. https://www.qbcc.qld.gov.au/running-your-business/contracts/retentions-securities
2. NSW Government. Retention money held by head contractors. nsw.gov.au. https://www.nsw.gov.au/housing-and-construction/compliance-and-regulation/security-of-payment/retention-money
3. Queensland Building and Construction Commission. Trust accounts. qbcc.qld.gov.au. https://www.qbcc.qld.gov.au/running-your-business/trust-accounts
4. Olvera Advisors. Australia’s Construction Sector: 2024 Year-In-Review. olveraadvisors.com. https://olveraadvisors.com/insolvency/australias-construction-sector-2024-year-in-review/
5. Contracts Specialist. Retention Release Process NSW Construction Projects. contractsspecialist.com.au. https://www.contractsspecialist.com.au/retention-trust-release-retention-release-overview-nsw/
Related Articles


The AI Construction Operating System
One platform, one data model, every project. Built in Australia, for the world.
YOUR DATA, PROTECTED
Hosted on AWS Sydney with Australian data residency.


GET THE MOBILE APP
Platform
Solutions
© 2026 Plexa Pro Pty Ltd. ABN 63 668 433 136